The fact that such situations occur more often than one might assume is due to the structural nature of payment delays when making international payments. Finding out what causes them is the first step towards avoiding them.
Why International Payments Get Delayed
International payment delay isn’t always caused by one single mistake. More often, it’s the result of several overlapping factors – each adding hours or days to what looks like a simple transaction on paper.
The SWIFT international network, correspondent banking chains, local compliance frameworks, and currency conversion mechanics all interact with each other in ways that are rarely visible to the sender. An operation that seems simple enough to you can actually go through as many as three or four organizations.
Intermediary and Correspondent Banks
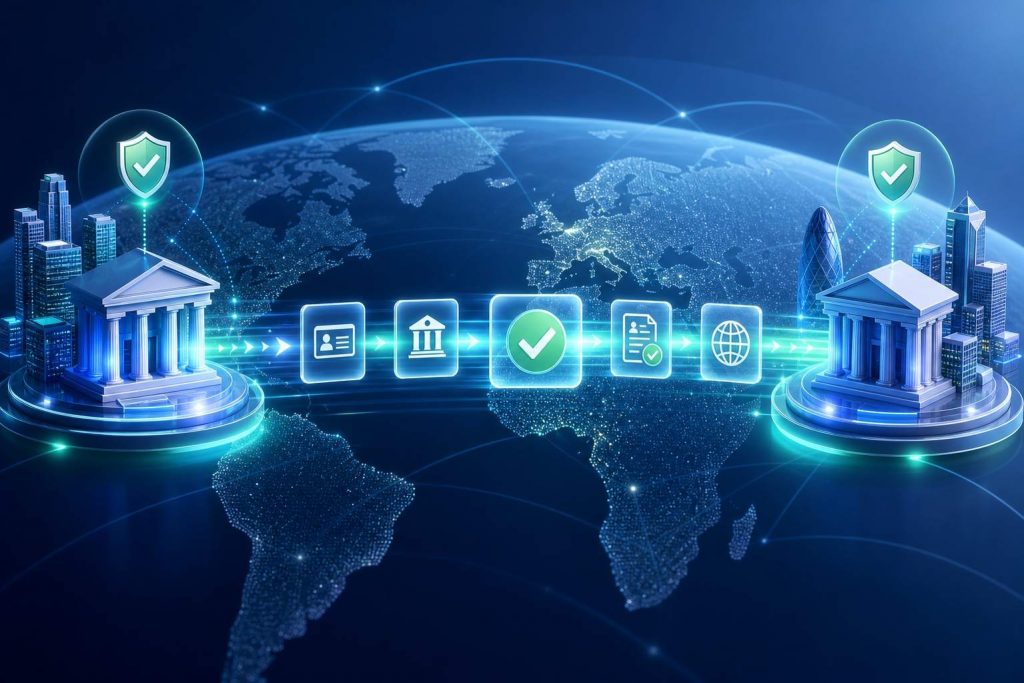
Most international bank transfers don’t go through straight from the sending to the recipient bank account. They pass through a chain of correspondent banks – institutions that hold accounts with each other and act as relay points across different jurisdictions.
The individual correspondent banks add their own process delay, fee deduction, and sometimes compliance checks. A payment route that passes through two or three intermediaries may take significantly longer than a direct one, and the sender often doesn’t have information where the transaction currently is.
In reality, for international transactions made between two average jurisdictions, there may be a local sending bank, regional hub bank, correspondent bank on the global level, and local receiving bank. In total, it makes four independent systems handling your money and, consequently, four independent sources of delay.
Compliance and AML Checks
Compliance checks are one of the most frequent causes of international payment delay that businesses don’t anticipate. Banks are legally required to screen transactions for AML (Anti-Money Laundering) and KYC violations, sanctions exposure, and suspicious activity patterns.
A transaction which has been detected by automatic checks can be subject to manual verification – without the sender being notified. The triggering factor is not always apparent and might range from unusual currency combinations to an unknown receiver, invoice value that doesn’t fit the established pattern, or jurisdictions that require increased attention due to higher regulation.
The result is a transfer’s delay, with both sides unaware of the reason. This is where many businesses face problems – not because anything is wrong, but because the paperwork wasn’t designed for this purpose in mind.
Incorrect or Incomplete Payment Details
- One wrong digit in an IBAN.
- A SWIFT code for the wrong branch.
- A beneficiary name that doesn’t exactly match the account registration.
Any of these can result in an international wire transfer delayed by days – or, in some cases, returned entirely.
Banks don’t always flag these errors immediately. The transfer may reach an intermediary, fail a matching check, and then sit in a manual exception queue before anyone contacts the sender. By that point, the business has already missed its deadline.
Cut-Off Times, Weekends and Public Holidays
Transfer delay often has nothing to do with compliance or routing – it comes down to timing. Most banks operate with daily cut-off times – a point after which payments submitted that day won’t begin processing until the next business day.
A payment submitted at 4 PM on a Friday in one jurisdiction may not begin moving until Monday morning in another. Add a public holiday in the receiving country, and the timeline extends further. International business payment flows cross multiple calendars – and the combined effect of cut-off windows and non-working days can add two to four days to an otherwise clean transfer.
Currency Conversion and FX Processing
When a payment involves currency conversion – particularly in less liquid currency pairs – FX processing adds another layer of complexity. The bank or intermediary must source the currency, apply the exchange rate, and complete the conversion before the funds can continue along the payment route.
FX deals are settled only during certain times of the day. If yours is sent during any other period, it will have to wait. For exotic currency corridors, liquidity constraints can extend processing time beyond what the sender would ever expect from a “standard” international wire.
How to Avoid Payment Delays: Practical Steps
The good news is that most payment delays in international transfers are preventable. They require preparation, not luck.
Verify Recipient Details Before Every Transfer
Before initiating any international bank transfer, check the following:
- IBAN – confirm every digit, including country code and check digits
- SWIFT/BIC code – verify it matches the correct branch, not just the correct bank
- Beneficiary name – must match the account registration exactly
- Transaction purpose / payment reference – many receiving banks require a clear description, especially for regulatory reporting
- Intermediate bank details – if required by the receiving bank’s local banking system
A mismatch in any of these fields doesn’t always produce an immediate error. Often it produces a delay – and a request for correction that adds days to the timeline.
Prepare Documentation in Advance
Should your payment consist of a significant amount, an uncharted currency corridor, or even a counterpart you have never done business with before, compliance papers must be prepared before the payment is sent.
Documents that commonly resolve compliance holds include:
- Signed commercial contract or agreement
- Invoice matching the payment amount and description
- Proof of goods or services delivered
- Company registration documents for new beneficiaries
- Purpose of transfer explanation for unusual transaction types
Having these materials prepared means that when a bank’s AML system flags a transaction for review, resolution takes hours instead of days.
Choose the Right Payment Route
Not all payment routes are equal. A direct relationship between your sending institution and the receiving bank – or a provider with access to local clearing networks – removes one or more intermediary steps from the chain.
When choosing a financial infrastructure partner, ask specifically:
- How many intermediary banks does this payment route typically involve?
- Does the provider have direct access to local settlement networks in the destination market?
- What is the average processing time for this specific currency corridor?
A shorter route means fewer compliance screenings, fewer fee deductions, and less time waiting in queues you cannot see.
Time Your Payments Strategically
To avoid cross-border payment delays caused by cut-off times and holidays:
- Send payments before 11 AM in the sending bank’s time zone if possible
- Avoid initiating international wire transfers on Fridays, especially for time-sensitive flows
- Check public holidays in both the sending and receiving jurisdiction before scheduling large payments
- Build an extra business day of buffer into payment schedules whenever crossing multiple time zones
This is basic operational discipline – but most businesses only learn it after the first missed deadline.
Work with a Provider That Has Real Payment Infrastructure
There is a large difference between a payments provider that has its own banking network, and one that only aggregates access to others.
An aggregator adds another layer to an already long chain. Payments providers that have direct connections with the banking network, as well as experience in working within local clearing facilities, are able to deal with problems much quicker – and in many cases, avoid them altogether.
This is the logic behind FinClub. The platform combines access to global payment infrastructure, 100+ currencies, multi-currency account management, and 24/7 human support – specifically designed for businesses that cannot afford to wait three days for an explanation of why a transfer is delayed.
For companies working with complex cross-border flows, the right infrastructure partner isn’t a privilege – it’s part of the payment plan.
What to Do If Your Transfer Is Already Delayed
Even with good preparation, an international wire transfer delayed situation can occur. Here is what to do.
Contact Your Sending Provider First
The first step is always to contact the institution that initiated the transfer – your bank or payment provider. Ask for:
- Confirmation that the payment was sent (not just submitted)
- The exact date and time it entered the network
- The current status and last known location of the transaction
In many cases, the sender knows where the hold occurs almost immediately. What feels like a missing transfer is often a payment waiting in a compliance queue at a specific institution – and knowing where it is makes resolution significantly faster.
Check with the Receiving Bank
At the same time, the receiver needs to get in touch with the receiving bank in their locality along with the reference number and other details of the payment being made. Occasionally, the problem of delayed payment is sorted out at this stage itself since the money has been received but not yet posted.
Choose the Route Before You Send the Payment
Most delays happen at points the sender never sees: correspondent chains, compliance queues, FX windows. The practical way to avoid them is not to react faster – it’s to set up the right infrastructure in advance.
Talk to the FinClub team
We’ll review your payment corridors, show where the time goes, and suggest a route without unnecessary intermediaries.
Frequently Asked Questions
How Long Does an International Transfer Normally Take?
The SEPA payments in the EU are usually settled after one business day. The normal SWIFT payments that are conducted in major markets usually take 1-3 days to settle. However, in case where the currency pairs are less common or involve the use of different correspondent banks, the settlement time may take between 5 and 7 business days.
Can Compliance Checks Be Avoided?
No – and they should not be. AML, KYC, and sanctions screening are legal requirements for financial institutions globally. What business can do is to minimize being unnecessarily flagged through having correct payment information, complete documentation, and clear description of the purpose of the transactions.
What Is the Safest Way to Send a Large International Payment?
For high-value transfers, the safest approach combines: verified recipient details checked directly with the counterparty (not just via an email check), preparation of full compliance documentation before the transaction takes place, payment channels without intermediaries, and a payment service provider that offers support specifically to help facilitate the transaction if it is delayed.
Why Does the Same Payment Route Sometimes Take Different Amounts of Time?
There are several factors that could affect the amount of time needed to process a particular payment path from one transaction to another. These include: the results of compliance checks performed (whether automatic or manual), changes in correspondent banking chains, FX liquidity during the process of currency exchange, cut-off times and if any party on the path is in shortened hours due to holiday season. Delay in cross-border payments doesn’t have a single reason – it comes down to how things line up at a particular point in time.